


DISCLAIMER & DISCLOSURE: The author holds an investment in Ashtead Technology at the date of publication but that may change. The views expressed are those of the author and may change without notice. The author has no duty or obligation to update this information. Some content is sourced from third parties believed to be reliable, but accuracy is not guaranteed. Forward-looking statements involve assumptions, risks, and uncertainties, meaning actual outcomes may differ from those envisaged in this analysis. Past performance is not indicative of future results. All investments carry risk, including financial loss. This analysis is for educational purposes only and does not constitute investment advice or recommendations of any kind. Conduct your own research and seek professional advice before investing.
Why Should I Care
If you’re a GARP investor, then you’ll be hard pressed to find a better opportunity in the market than this one right now.
Imagine a business that came public in 2021 and has compounded revenue at 41% annually since. Earnings per share have grown at 37% over the same period, without any help from buybacks. Returns on invested capital sit at 22.7%. Growth has been driven by a disciplined roll-up strategy that continues to expand the opportunity set.
On the surface, this is exactly the kind of company the market usually rewards. High growth, strong returns, and a clear path to reinvest capital at attractive rates. Forward expectations suggest that this trajectory is not slowing down. If anything, the runway into the end of the decade still looks strong.
You would expect a premium valuation, right?
Instead, the business trades at just 7.9 times trailing adjusted earnings.
The numbers look exceptional. The valuation implies the opposite. The question is simple: “Which one is wrong?”
Let’s dig in to the detail.
The Backstory
Ashtead Group plc didn’t begin as a global scale operator. It started in 1947 as a village plant hire business in Surrey, UK, serving local construction demand with a limited asset base and a simple rental model.
For decades it remained small. At the point of its 1984 management buyout, the business was generating roughly £1 million GBP in revenue. Yet what followed from that base has been one of the more aggressive compounding stories in British corporate history.
The inflection point came in 1990 with the acquisition of the US business, Sunbelt Rentals, for £17.5 million. The price understated the strategic significance. That deal shifted the company’s centre of gravity to North America, placing it into a deeper, more fragmented rental market with higher long-term growth potential. Over time, that decision came to define the business. It embarked on a mission to consolidate the industry through strategic acquisitions: a roll-up strategy (Brad Jacobs style).
It’s growth has been astounding, achieving a 20% CAGR on its share price over the past decade, and a 13% CAGR over the last 30 years.
The playbook was executed with consistency. Capital was recycled into a steady stream of bolt-on acquisitions, building density across local markets while expanding into higher value verticals such as climate control and disaster recovery. The model evolved from general equipment rental into a broader infrastructure support platform. Scale improved utilisation, purchasing power and customer stickiness.
The Sunbelt acquisition mattered. It was the pivot that saw the business move from being exclusively UK focused, to now seeing more than 85% of group revenue (exceeding $10 billion), alongside the vast majority of profits, generated in the US. It fundamentally became a North American earnings engine and is the second-largest equipment rental company globally, with a market capitalisation north of $30 billion.
It explains why, as of March 2026, the group has rebranded to Sunbelt Rental Holdings, with its primary listing moved to the United States under the ticker SUNB, alongside a secondary listing in London.
But this is not a story about Ashtead Group, the focus here is a smaller, less visible business that it spawned: Ashtead Technology Holdings (AT.L), listed in London.
It began as a small, non-core division within the broader group, but was eventually spun out. The rationale was simple. It sat outside the parent’s core equipment rental focus, even if the underlying model shared clear similarities.
Today, the spun out Ashtead Technology Holdings is deploying a remarkably similar playbook to its parent, growth through roll-up acquisitions to gain a dominant market position, albeit in the sub-sea specialist equipment space. It is now enjoying similarly impressive compound growth rates.
The sub-sea business was founded in 1985 in Aberdeen, a city shaped by the development of the North Sea oil and gas industry. Ashtead Technology grew within a specialised offshore ecosystem where reliability and technical capability were essential.
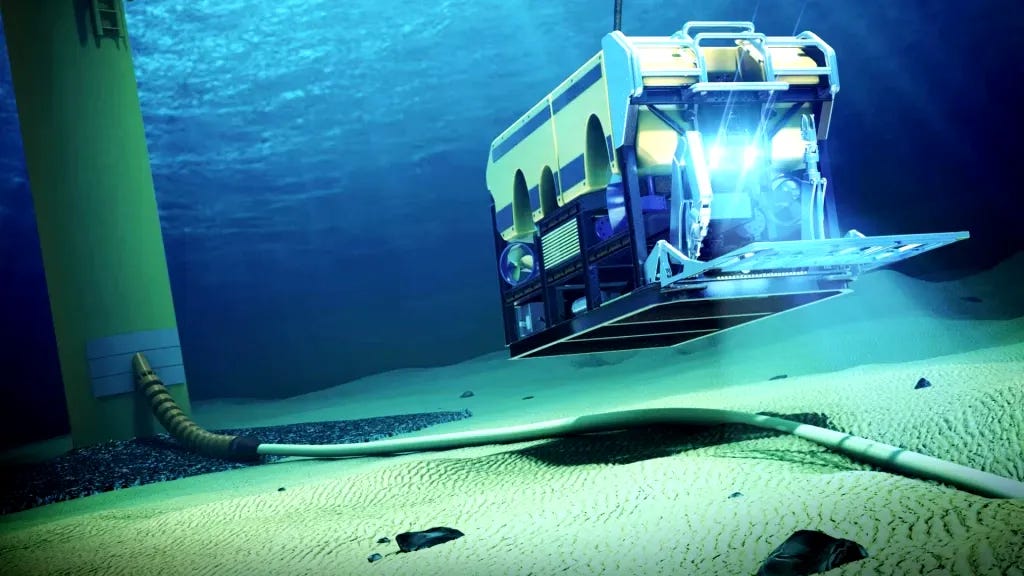
Its focus was subsea electronics rental. This was not generalist equipment hire. The inventory consisted of highly specialised tools such as sonar systems, ROV sensors, and hydrographic survey equipment used for underwater inspection and data collection. These assets required calibration, maintenance, and technical support. They also had to integrate seamlessly into complex offshore operations, which raised the bar for service quality and expertise.
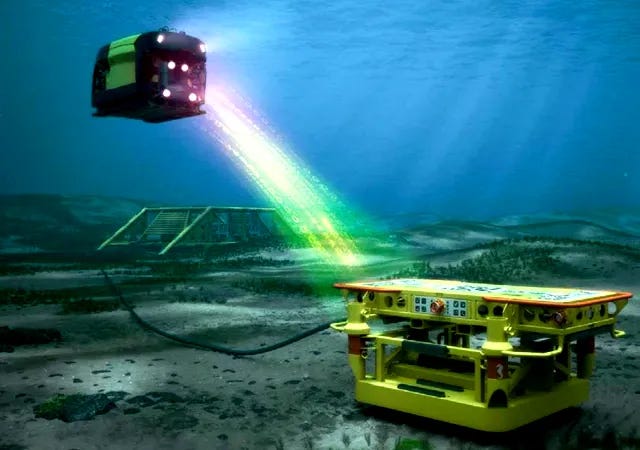
From the outset, the business operated in a different economic environment to its parent. Demand was linked to offshore energy cycles rather than construction activity. Asset complexity was higher, utilisation patterns were different and customer relationships were more embedded in operational processes. Over time, that divergence became more pronounced, setting the foundation for what would eventually become a standalone business with its own strategy and trajectory.
The separation came in 2008. Backed by Phoenix Equity Partners, management executed a buyout at roughly £95.6 million. Independence removed any strategic constraint. Capital and attention could be directed solely at offshore energy, where equipment complexity, utilisation and service intensity all compound differently to general rental. It shifted the centre of gravity from being a division to being a focused operator.
The next inflection came in 2016 when Buckthorn Partners and APICORP took ownership. This is where the model started to evolve in a more deliberate way. The business moved beyond pure rental into integrated subsea solutions. That shift sounds incremental but it changes the economics. Rental is transactional. Solutions embed you deeper into customer workflows, extend duration and increase switching costs. The strategy that followed was straightforward in design and demanding in execution. Build out capability through acquisition, extend geographic reach and layer services around a core fleet.
The acquisitions in that period were carefully crafted. TES Survey Equipment Services established a foothold in the Middle East. Forum Subsea Rentals was more consequential, scaling the fleet and consolidating market position. Welaptega Marine added inspection and asset integrity, moving the company closer to critical maintenance workflows. Aqua-Tech Solutions strengthened exposure to the Gulf of Mexico. Each deal added a piece of the same puzzle. More equipment, more services, more proximity to the asset lifecycle.
By the time the company came to market in November 2021, the shape of the business had already changed. The IPO on AIM (London Alternative Investment Market) raised £52 million and valued the company, post money, at around £129 million. The stated use of capital was to delever the balance sheet and continue acquiring. The more important backdrop was demand. Offshore wind was moving from concept to capital cycle. Subsea infrastructure was no longer just oil and gas. The same capabilities began to apply to installation, inspection and maintenance of renewable assets.
The acquisition cadence didn’t slow after listing. WeSubsea and Hiretech extended capability into dredging and decommissioning. ACE Winches added heavy-duty lifting and mooring, which sits directly in the critical path of offshore wind installation. Seatronics and J2 Subsea, acquired from Acteon Group, expanded the fleet materially and deepened technical capability in ROV tooling. The pattern is consistent. Increase fleet density, broaden services, and move closer to mission-critical activity.
What followed was a period of rapid scaling. Revenue quadrupled post-IPO, and the mix shifted meaningfully towards renewables. By October 2025, the company moved to the Main Market London Stock Market with a premium listing. That step was less about optics and more about access. Deeper liquidity, broader institutional ownership and a platform that can support continued consolidation in a fragmented market.
Allan Pirie, CEO, has led the business for over 15 years, across private equity ownership, the IPO and the uplisting. That kind of tenure is not common in roll-up stories. Ingrid Stewart, CFO, joined ahead of the IPO and has been central to capital allocation and deal execution. Beneath that, much of the senior team has remained in place. That stability matters because the strategy relies on integration discipline and domain expertise. This is not financial engineering. It is operational accumulation.
The result is a business that looks very different from where it started. From a niche rental arm to a scaled subsea technology platform embedded across the energy infrastructure lifecycle. It now sits in the flow of both traditional offshore energy and the build-out of offshore wind. That dual exposure is the outcome of a long, consistent strategy applied across multiple ownership cycles. Growth in both segments ebbs and flows, so having exposure to both smooths the growth profile of Ashtead Technology. In FY25, growth in renewables was impacted by the Trump administration policy of favouring of oil and gas over renewable energy generation: “Drill, baby drill!” is Trump’s mantra.
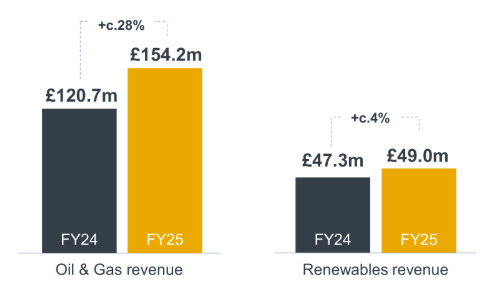
Given geo-political issues in the middle east preventing the free flow of oil through the Straits of Hormuz, offshore activity is likely to pick up in the year ahead. Ashtead Technology is well placed to ride that tailwind.
The Numbers
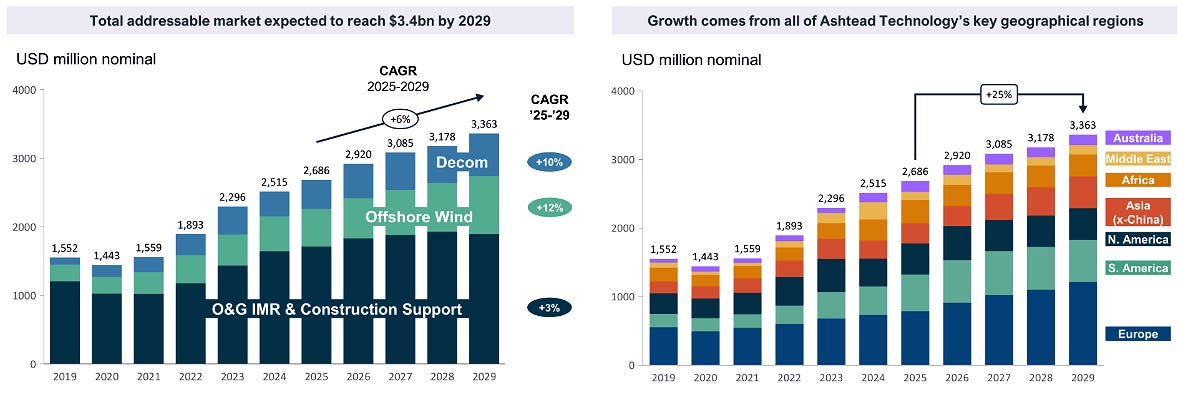
The company has ~650 employees with market leading domain knowledge and expertise, enabling it to gain the trust of customers to undertake complex underwater engineering and project execution. Complimentary acquisitions over time have resulted in the business now being able to offer a flexible service and an equipment selection to meet the wide ranging needs of customers across the full lifecycle of a subsea energy infrastructure programme. It is now, in many respects, a one-stop shop with a comprehensive offering that others are unable to match. This helps to increase the TAM of the company (forecast to grow at 6% CAGR through 2029, see chart below). Ashtead Technology is also expanding its range of proprietary in-house designed, engineered, assembled and operated technologies. Collectively, this provides Ashtead Technology with unrivalled capability that cannot be bought by competitors, positioning it well for future growth. This is a business with a deep moat, as demonstrated in its strong unit economics.
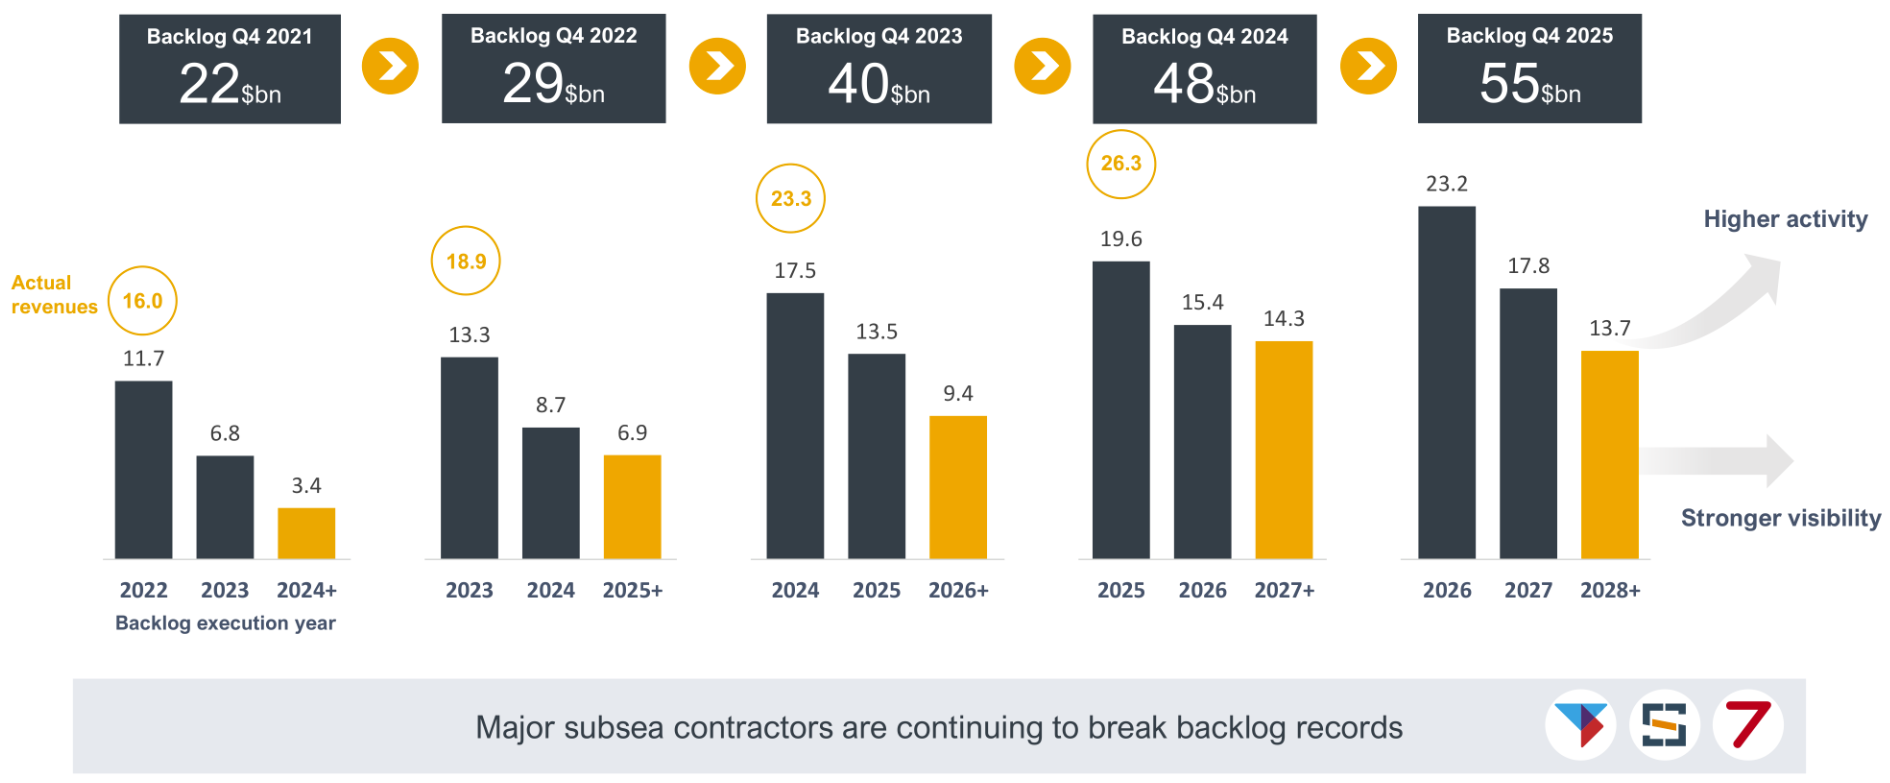
Increasing backlogs underpin future performance and provide good forward visibility.
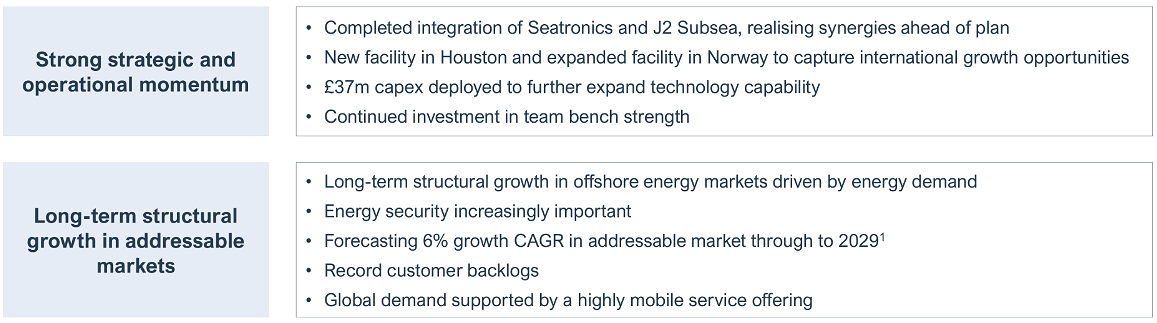
The FY25 earnings continue to impress. Revenue growth was 22% on a constant currency basis, 21% in real terms (19% acquired, 3% organic and a 1% headwind due to adverse FX movements). It generated a 29.1% adjusted1 EBITA margin and 10% adjusted EPS growth. Strong strategic and operational momentum continues and the growth prospects look impressive. Importantly, second half revenues were 5% up on the first half, so momentum shows no sign of abating.
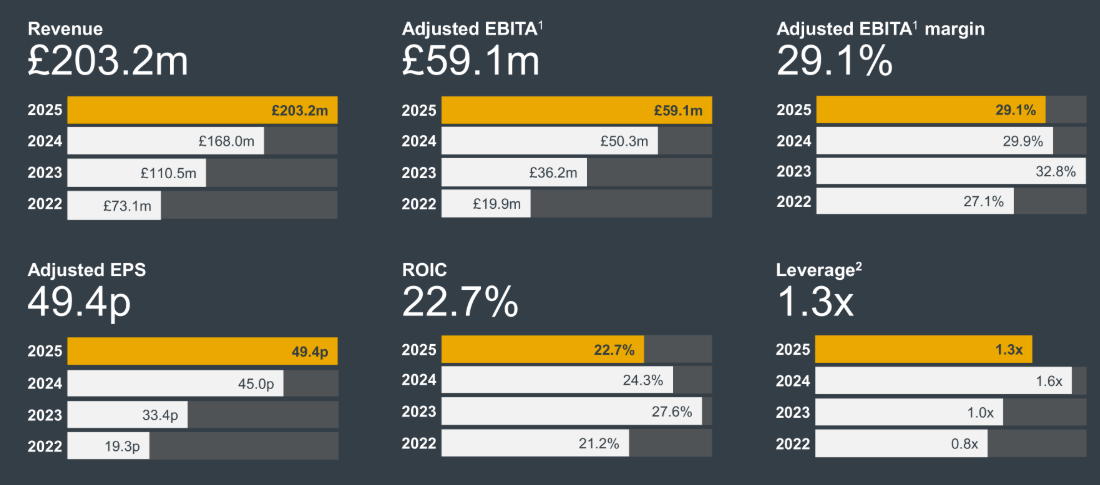
Meanwhile the balance sheet looks stronger as leverage is reduced to a mere 1.3x. Financing costs were higher than normal in FY25 as the result of recent acquisitions, but the deleveraging of the balance sheet ought to normalize interest expense in FY26, adding another boost to expected earnings.
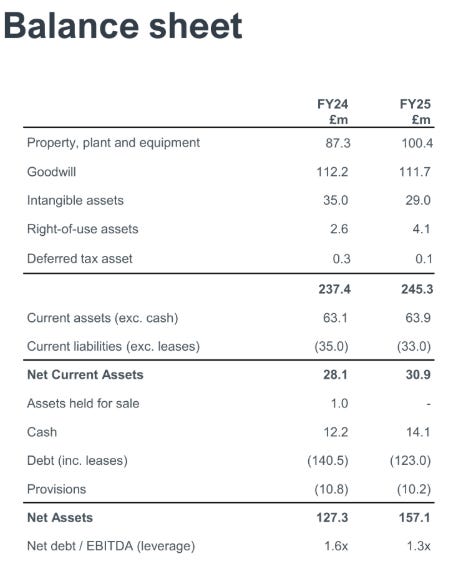
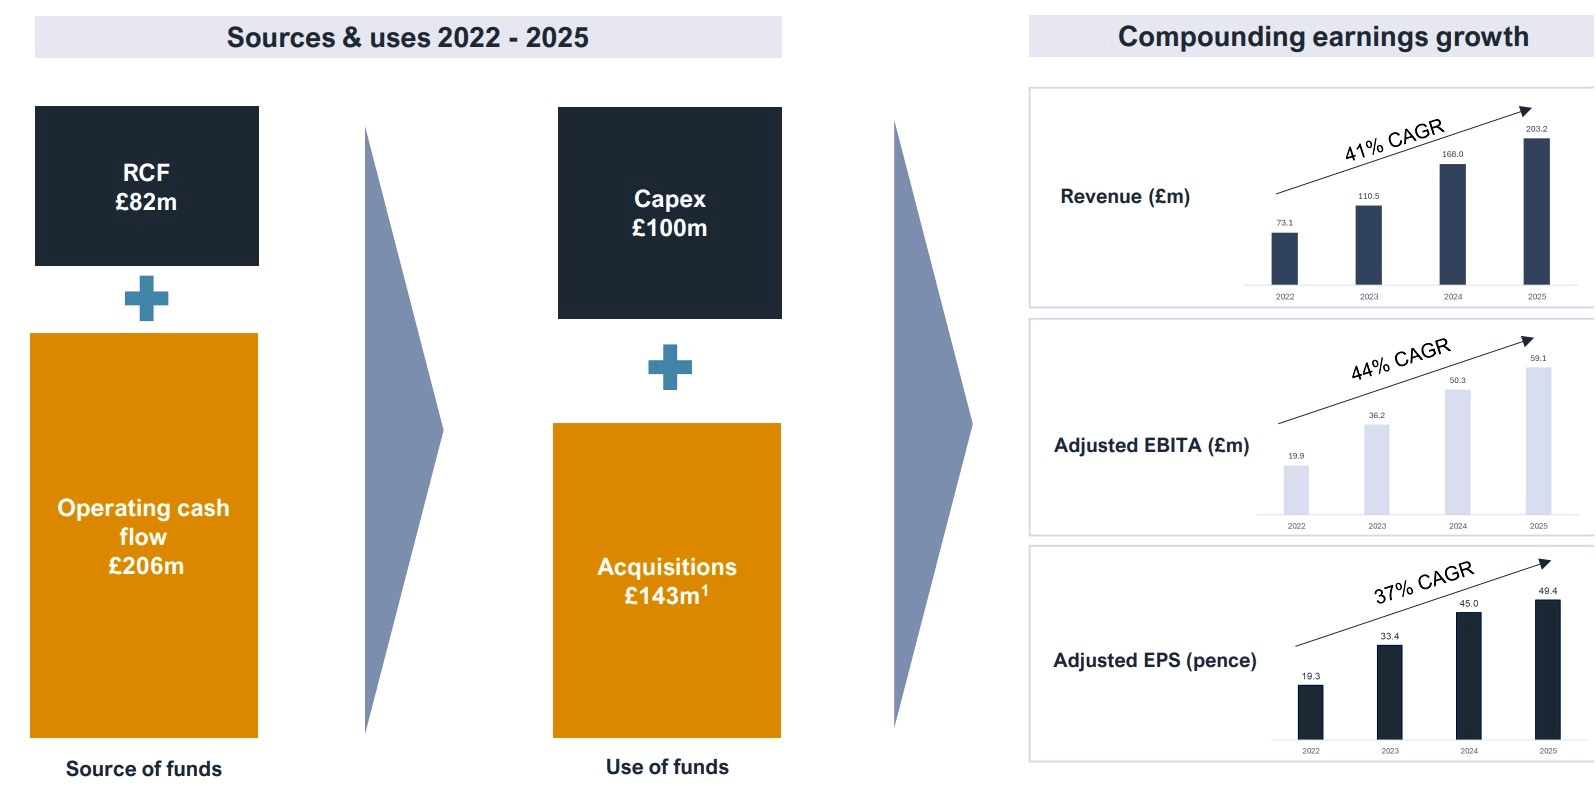
The company is very disciplined and runs working capital at 16% of revenue, targetting 15%. Growth is funded primarily from operating cash flows, augmented with debt on a revolving credit facility.
The results speak for themselves. In the 4 year period 2022-2025, revenue has grown at 41% CAGR, adjusted EBITA at 44% CAGR and adjusted EPS at 37% CAGR.
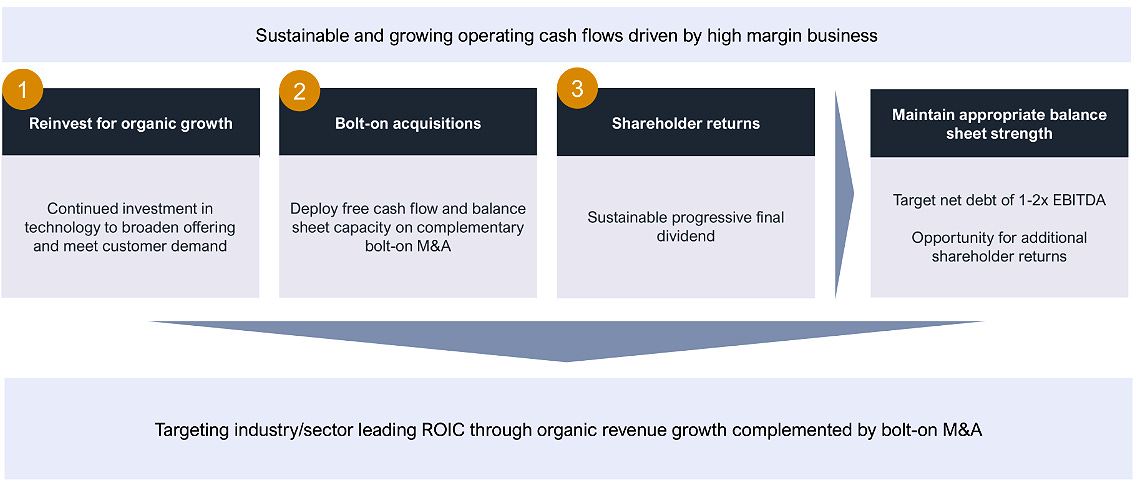
This brings us to the company’s capital allocation policy. Reinvesting in organic growth and seeking out new bolt-on acquisition targets remains the focus, as it should be. Maintaining balance sheet strength is also a core objective.
The only real criticism of management, and it is a very British one, is the self-imposed constraint on capital allocation through a progressive dividend policy. It limits flexibility at exactly the moments when flexibility matters most. There are two arguments that can be made here:
A dividend is not a neutral act. It is a partial liquidation of the balance sheet. It should only be paid when the business has exhausted its reinvestment opportunities. Returning cash to shareholders while simultaneously relying on debt to fund operations is economically incoherent. It amounts to borrowing to pay a dividend.
The opportunity cost is obvious. With adjusted EPS of 49.4 pence and a share price of 380 pence, the business is capitalized at 7.9 times earnings despite delivering revenue and earnings growth in excess of 35% CAGR. That is a material disconnect from intrinsic value. In such situations, capital should be directed toward repurchasing shares. Buybacks at this valuation are not cosmetic. They are accretive, improve capital efficiency, and concentrate ownership at a discount to intrinsic value. Contrary to popular belief, and to that of management, repurchases should never be construed as being interchangeable with a dividend (click to learn more).
Management have been lobbied by shareholders on this point year after year, but refuse to change their position.
Is Ashtead Technology Holdings A Good Investment?
After reaching peaks above 800p in mid-2024, the share price saw a dramatic correction, falling as low as 346p by mid-2025.
The company reported significant project delays in the first half of 2025, particularly in the US market, which dampened investor confidence. This was caused by the new Trump administration and its shift away from investment in renewables.
Changes in trade policies and tariff uncertainties caused some clients to pause expansion plans for survey work and rental gear. This too was a temporary headwind.
As such, there is no structural issue within the business, merely a change in the macro environment.
Tariffs have since been deemed illegal by the Supreme Court, while Ashtead is technology agnostic: Its equipment is used both for offshore renewables (principally wind), and also for the oil and gas sector.
This means that neither of these issues is really an issue. They don’t impact the long-term prospects of the business and the FY25 figures support that.
After a massive rally from 2021 to 2024, the stock was aguably priced for perfection. It was way too expensive at its peak. When the growth story shifted from "explosive organic growth" to "steady acquisition-led growth," a correction was inevitable, but has the pendulum swung too far the other way?
On the face of it, the stock looks mispriced and way too cheap at the moment. It is arguably due a re-rating. The share price has been moving higher, slowly, off its 2025 low, but it should have much further to go.
That said, balance matters. There are risks that need to be acknowledged.
Customer concentration is one. The business has meaningful exposure to a relatively small group of large clients, primarily energy majors and offshore contractors. Layer onto that the inherently cyclical nature of offshore energy, and you have a setup where a downturn could pressure both utilisation and pricing at the same time.
However, context is important. The industry appears to be in an upward phase of the cycle, with strong visibility likely through to the end of the decade. And while Ashtead is reliant on a small number of customers, the relationship runs both ways. These customers are not incentivised to own large fleets of specialised subsea equipment that sit idle between projects. Renting on a flexible, pay-as-you-go basis is economically rational. That is the core of Ashtead’s value proposition.
The competitive landscape reinforces this positioning.
Teledyne Marine operates primarily as a manufacturer and innovator. It builds high-spec components that underpin subsea operations, but it is not a rental platform. It supplies the tools rather than managing their deployment.
Oceaneering is the closest scaled competitor, but its model is structurally different. It is vertically integrated, offering bundled solutions through its own ROV fleet and personnel. Ashtead takes the opposite approach. It provides a broad catalogue of equipment sourced from multiple manufacturers, allowing customers to select the best tool for each job without being locked into a single ecosystem.
The evolution of Acteon Group is also instructive. Its 2024 acquisition by Buckthorn Partners and One Equity Partners marked a strategic shift. Acteon is becoming more focused on engineering-led services such as foundations, moorings, and decommissioning, while divesting rental-oriented assets like Seatronics and J2 Subsea. Ashtead moved in the opposite direction, acquiring those businesses to expand its equipment base and deepen its rental platform. Acquisitions like Seatronics and J2 Subsea consolidate these capabilities into a broader, more integrated offering that is difficult to replicate organically. The result is two companies that still compete, but with increasingly different strategic focuses and priorities.
Below these big names sits a fragmented layer of specialists such as Subsea Technology & Rentals, Kongsberg Maritime, and EIVA. Each focuses on narrow capabilities across survey, positioning, or sensing. This fragmentation is exactly what enables Ashtead’s roll-up strategy.
All of this points to a clear conclusion. Ashtead has carved out a distinct niche within the subsea market. Its model combines breadth of equipment, capital efficiency for customers, and a scalable acquisition strategy.
That shows up in the numbers. Strong margins indicate pricing power. Sustained growth indicates demand. Together, they suggest durable earnings power.
The question is not whether the business is good. It is for how long will the market continues to misprice it. Either a re-rating will occur, or else it would come as no surprise if Ashtead Technology becomes the subject of a takeover attempt. It just looks too cheap.
This post was not intended to be a deep dive, but instead an introduction to this very interesting opportunity. If you want to investigate further, I recommend the following two Substack posts which do a wonderful job of diving deeper into Ashtead Technology:


Adjusted EBITA is calculated as operating profit adjusted to add back amortisation, FX movements and items considered one-off in nature. The company is not financial engineering good results. Depreciation and other real ongoing costs are not deducted from its numbers, hence EBITA rather than EBITDA.
As the cyclical soft patch passes and customer backlogs convert into mobilised campaigns, organic growth should re-accelerate toward management's low-double-digit target. This alone would remove the overhang on the multiple. Furthermore, the consensus estimates are completely missing the company's second engine: its disciplined M&A machine. With net leverage at just 1.3x and a history of buying at 4.6x EBITDA, management has significant firepower to make accretive acquisitions, a value driver the market is not pricing in at all.
The company is a high-return, asset-light compounder trading at a deep discount to its peers. It earns a 22.7% return on invested capital and generates EBITDA margins above 40%, yet it trades at just 5.4x EV/EBITDA. For context, lower-growth, lower-return rental names like United Rentals and Sunbelt trade between 8x and 10x. The market is effectively pricing Ashtead for stagnation, despite its track record and the record $55 billion backlogs of its Tier-1 customers, which point toward a re-acceleration in activity. This is a classic case of a high-quality business being valued as if it were mediocre, creating a compelling entry point.
The path to a re-rating is clear and requires no heroic assumptions. If Ashtead's multiple were to simply converge toward the 7x to 8x range of its peers, it would imply upside of 48% to 76% from the current share price, without assuming any organic growth or M&A upside. The board's aggressive performance targets, which tie management compensation to ROIC and EPS growth, further align interests with shareholders and underpin confidence in future execution. The company is well-capitalised and its free cash flow is set to inflect as the acquisition-related working capital build normalises and capex intensity peaks.
The only disappointment is the management's dogmatic approach to maintaining a progressive dividend policy, when the capital would be better served if allocated to repurchases of stock that trades at a huge discount to intrinsic value (so very disappointingly British!)
Nonetheless, patient investors are likely to reap a good reward.
A good note, but your dividend point feels misplaced given the total cost is around £1m and cashflow post capex and tax is around £23m. It really isn’t a huge drain on resources in my opinion. I agree with your assertion that with a lowly leveraged balance sheet it could be a takeover target.