


DISCLAIMER & DISCLOSURE: The author holds no small position in LSEG at the date of publication but that may change. The views expressed are those of the author and may change without notice. The author has no duty or obligation to update this information. Some content is sourced from third parties believed to be reliable, but accuracy is not guaranteed. Forward-looking statements involve assumptions, risks, and uncertainties, meaning actual outcomes may differ from those envisaged in this analysis. Past performance is not indicative of future results. All investments carry risk, including financial loss. This analysis is for educational purposes only and does not constitute investment advice or recommendations of any kind. Conduct your own research and seek professional advice before investing.
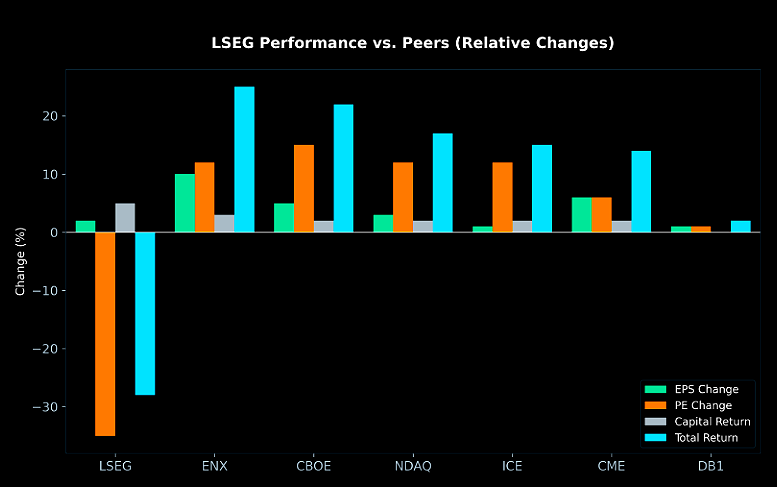
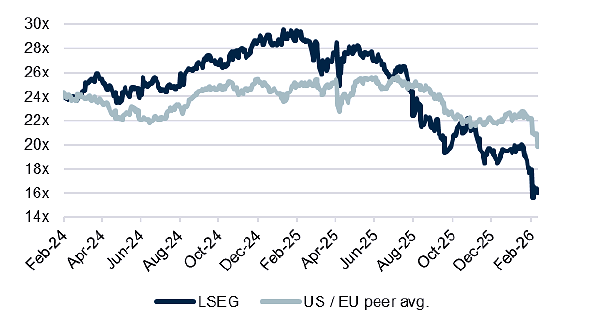
The London Stock Exchange Group has fallen around 30% over the past year significantly underperforming its US and European peers.
Zooming out further, it is clear to see that while other exchanges have seen their share price returns dip sharply, LSEG appears to have fared the worst.
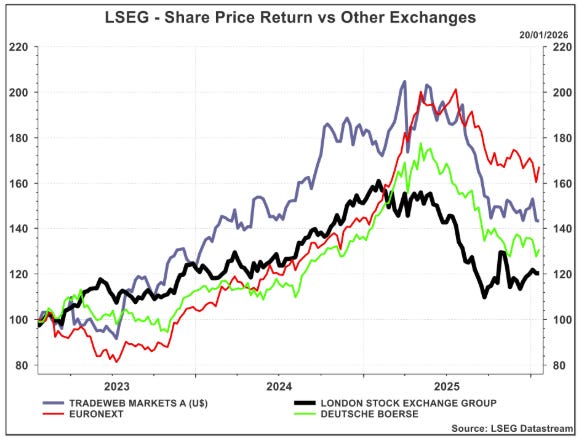
It seems that companies listed in London are somehow cursed with negative market sentiment.
Should LSEG move its listing to the US?
Wow, just imagine that!
Of course that will never happen, so let’s explore what’s going on. Has LSEG been over sold? Is this a good investment opportunity?
Excutive Summary
London Stock Exchange Group (LSEG) is a poorly understood business. Although it began as a market place for buying and selling shares, equity trading now accounts for only 5% of revenues.
Today, LSEG sells the tools that banks, hedge funds and trading firms all depend on: market data, indexes, risk intelligence, trading workflows and clearing infrastructure.
Every trade, portfolio decision and compliance check runs through some combination of these services.
The market’s current concern is that generative and agentic AI will weaken the economics of financial terminals and workflow products. The more likely outcome is the opposite. As AI becomes embedded inside financial workflows, the number of data queries, model checks, and compliance validations increases. Each of those interactions requires reliable, structured, proprietary data. That plays directly into LSEG’s core strengths.
The company’s strategy reflects this shift. Through its long term partnership with Microsoft and the “LSEG Everywhere” approach, LSEG is embedding its data directly into the tools professionals already use such as Excel, Teams and Copilot. The goal is simple: when AI runs inside financial workflows, it runs on LSEG data.
The result is a systemically important infrastructure business that benefits from the growth of financial data usage.
Tell Me More
London Stock Exchange Group has spent the last several years transforming itself from a regional exchange into a global financial data and infrastructure provider.
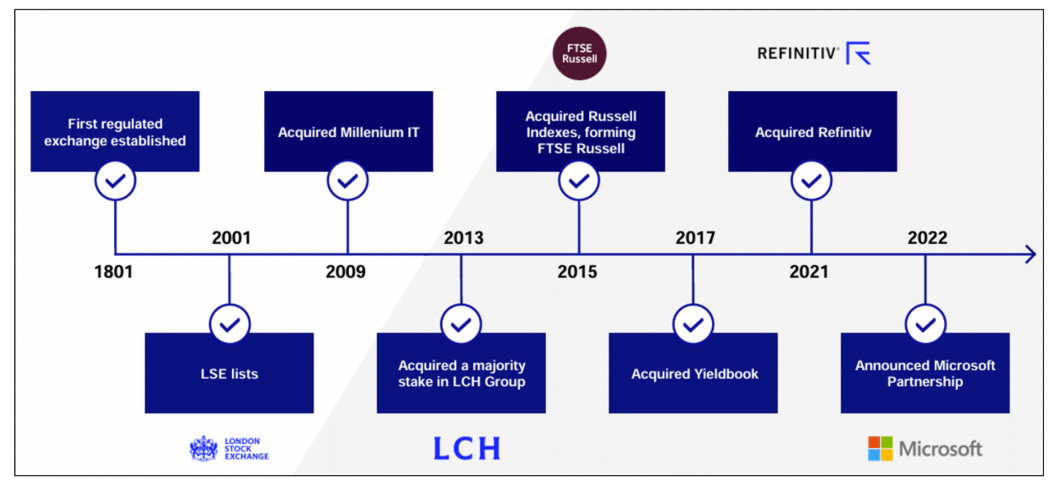
The Refinitiv acquisition was the turning point. That deal reshaped the company’s revenue mix and pushed the business toward recurring data and subscription income.
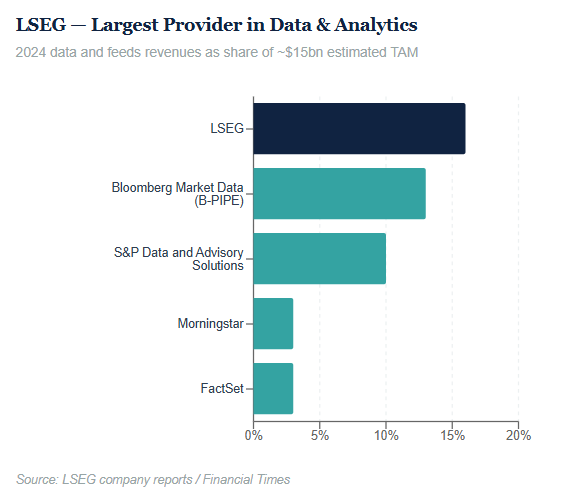
Today roughly 73% of group revenue is recurring, which gives the company unusually high visibility into cash flows (peer recurring revenues for comparison: Nasdaq 77%, Euronext 55%, ICE 51%, Deutsche Boerse 36%, CBOE 27% and CME 19%).
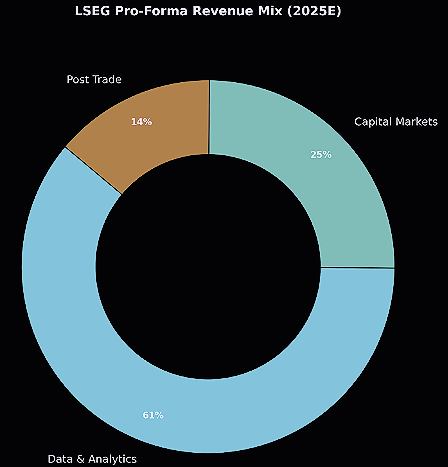
What sits underneath that revenue base is a set of assets that are deeply embedded in the functioning of global markets.
London Clearing House (LCH), the group’s clearing house, arguably its crown jewel, dominates the clearing of over the counter interest rate swaps. SwapClear processes more than 90 percent of cleared OTC interest rate swaps globally and holds around 80 percent market share across the major currencies. The product is embedded in dealer balance sheets and risk management systems, supported by long term bank partnerships that extend well into the next decade. Clearing infrastructure is extremely difficult to replicate because it depends on liquidity, regulatory approval and network effects between large banks.
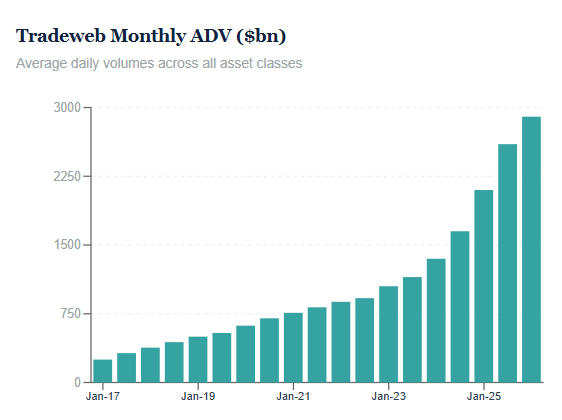
Tradeweb (TW) - [LSEG holds a 51% stake] - provides a different but related source of strength. The platform sits at the center of the long term shift toward electronic trading in fixed income markets. Average daily volumes now exceed $2.2 trillion. The platform benefits when markets become more volatile and when trading shifts away from voice broking toward electronic execution. The underlying trend has been steady for more than a decade and continues to expand across asset classes. The chart below demonstrates the Tradeweb average daily volume (ADV) growth trajectory across asset classes.
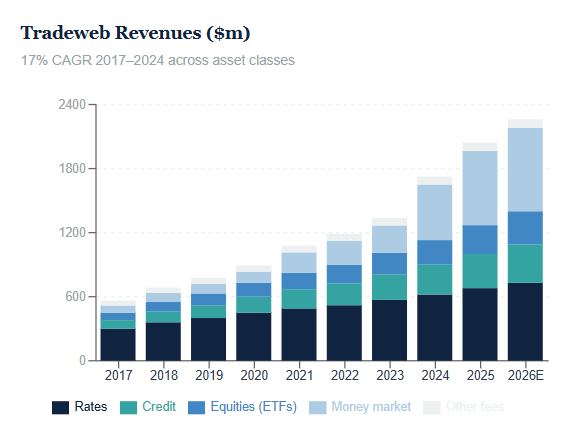
FTSE Russell contributes another important layer to the group. The index business generates high margin intellectual property revenue tied to the continued growth of passive investing. Its benchmarks support more than $1.4 trillion in ETF assets and continue to grow as asset managers increase their use of indexed strategies, particularly in fixed income. Alongside this, the Risk Intelligence division provides regulatory and compliance data services that have been growing at roughly 10% annually, supported by increasing global regulatory complexity.
Despite these strengths, the market has recently begun to treat LSEG as an artificial intelligence loser. The concern is that generative AI could weaken the value of traditional financial terminals and workflow products. Investors worry that large language models might replace parts of the information and research layer that financial data providers sell to institutions.
This narrative has weighed heavily on the share price. LSEG has significantly underperformed both the FTSE All Share and its US information services peers.
Yet the underlying exposure to AI disruption is often misunderstood. The most vulnerable activities are research and advisory workflows. Those areas represent a minority of the company’s business. The Workflows segment accounts for about 22 percent of group revenue, but the part most exposed to AI substitution represents roughly 7 percent of total revenue.
Much of the workflows business sits inside trading environments rather than research desks. Traders rely on extremely low latency data, tightly integrated execution systems, and infrastructure that must operate with near zero error tolerance. Generic AI tools cannot substitute for that environment. A trader operating in fixed income or equities generates several million dollars of revenue per year for a large bank. A small reduction in terminal subscription costs provides little incentive to risk operational disruption or regulatory issues.
The company’s data assets also represent a significant barrier. LSEG aggregates information from around 575 exchanges globally. That number is substantially higher than most competing platforms. The group also maintains a historical tick database that stretches back to 1996 (peer comparison: 2008 for Bloomberg and 2013 for FactSet). For machine learning and market modelling, long and consistent historical datasets are extremely valuable. Replicating that history is effectively impossible for new entrants.
The company’s partnership with Microsoft reflects this reality. Rather than attempting to compete directly with AI platforms, LSEG is integrating its data infrastructure with Microsoft’s cloud and productivity ecosystem.
The first stage of the strategy is the migration of roughly 350,000 users onto the Workspace platform, which will gradually incorporate natural language search and AI assisted workflow tools. Over time, the platform is expected to support agent based automation that can assist with complex financial analysis tasks while still relying on LSEG’s proprietary datasets.
The infrastructure behind this is substantial. LSEG processes around one billion data ticks per second and uses specialised timing systems to synchronize market data with extreme precision.
The group is also migrating approximately 33 petabytes of data to Microsoft Azure. This shift reduces the need for internal capital investment while improving accessibility for clients and developers.
A key part of the strategy is distribution. By embedding LSEG data inside Microsoft 365 applications such as Excel, Teams, and Copilot, the company places its datasets directly into the daily workflow of financial professionals. The goal is to ensure that AI tools still rely on LSEG as the underlying data source. If successful, AI does not displace the company’s data franchise. It increases the number of data queries and creates opportunities to charge for additional usage.
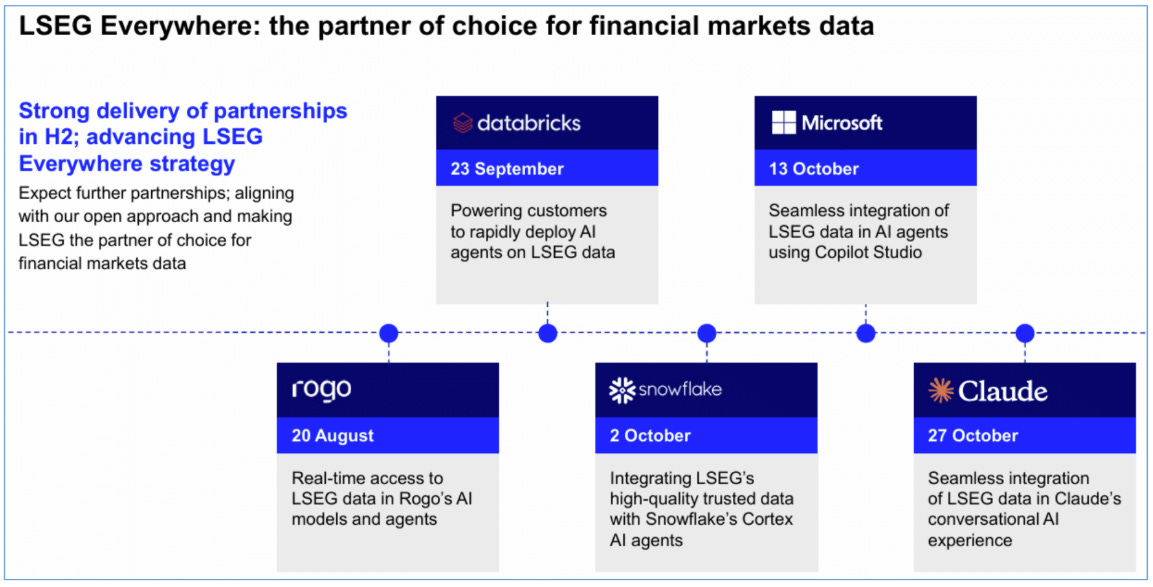
LSEG strategic partnerships began with Rogo and Databricks, but since expanded to include Snowflake, Microsoft and Athropic (Claude). In August 2025, the company partnered with Rogo, an AI platform used by investment banks and a Microsoft partner, allowing Workspace users to search, analyse and generate insights directly from LSEG datasets using AI models and agents. These tools can automate tasks such as preparing investment banking pitches and analysing market trends. A month later, LSEG announced a partnership with Databricks to make its data available natively within the Databricks platform through Delta Sharing. This allows financial institutions to combine LSEG’s raw tick and reference data with their own internal datasets and rapidly deploy AI agents for analytics, risk management and trading workflows. Together, the partnerships expand the ways LSEG’s data can be embedded into AI driven financial applications.
The Numbers
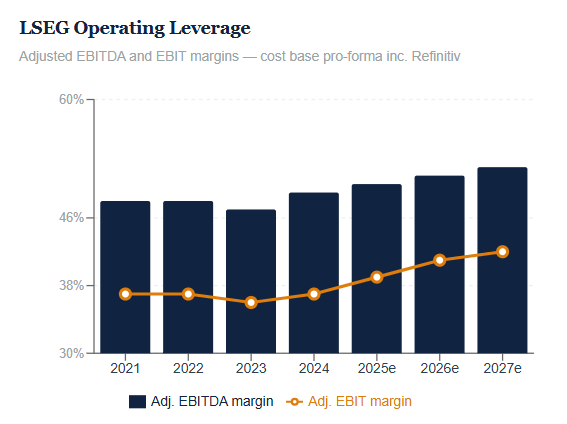
Financially the company remains strong. Adjusted EBITDA margins are approaching 50% and organic growth remains solid, see chart below:
Yet the market values the company at a large discount to comparable US information services firms. The shares currently trade at roughly 18 times forward earnings, compared with multiples above 30 times for companies such as S&P Global and MSCI.
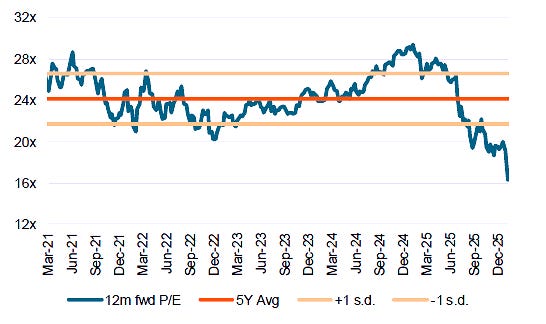
The gap becomes even wider when adjusting for LSEG’s 51 percent stake in Tradeweb. Removing that stake implies that the core LSEG business trades closer to 15 times expected 2027 earnings1. That multiple sits near the bottom of the exchange and financial data peer group.
The share price and the EPS numbers appear to be moving in opposite directions.
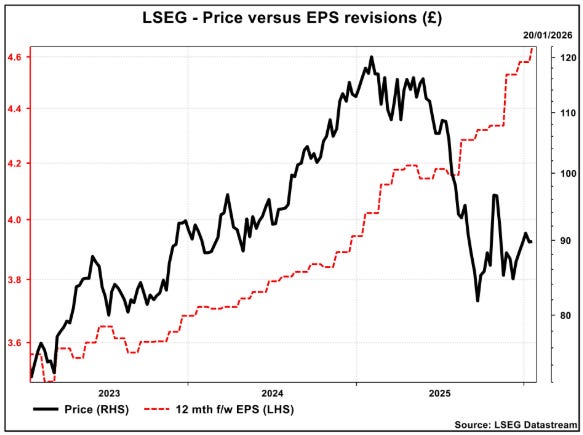
At current prices the market is effectively discounting several negative scenarios at once. One interpretation is that earnings expectations will be cut materially. Another is that workflows growth will stall while other data segments slow. The most extreme interpretation is that the market assigns little or no value to the workflows business at all, despite the company holding roughly 9 percent share of the global terminal market.
Management appears to view the valuation as unusually low. The company is “returning capital”2 through a £2.5 billion share buyback programme.
The company has a progressive dividend policy (so typically British!). This is a shame because at the current valuation, surplus capital applied to buy backs would be far more accretive for shareholders than dividends. Unfortunately, old-fashioned and misinformed British investors continue to demand dividends (a partial liquidation of the balance sheet), then they wonder why British companies underperform their international peers!?! In any event, the payout ratio is high, averaging ~60% of earnings, yielding ~1.6%.
Is LSEG A Good Investment?
The central issue for investors to ponder is whether the AI disruption narrative is correct.
The underlying numbers suggest that the exposure is limited and that AI is more likely to be a tailwind for the business than a headwind.
Progress on the Microsoft integration, the rollout of AI enabled tools and clearer disclosure around user growth could all help rebuild market confidence.
At present the shares appear to trade materially below the value implied by the company’s assets and long term cash generation. Some analysts are suggesting that the shares are trading at 66 pence on the pound, which implies ~50% upside from current levels around 80 GBX per share.
If the market agrees and gradually recognises this, the current valuation gap could close. Is LSEG at its current depressed price a good investment opportunity? Only you can decide. This is not investment advice, purely educational material.

Tradeweb is listed on NYSE, so the LSEG implied valuation is calculated using market prices - if the reader views Tradeweb as over valued, an upward adjustment should be made to the implied LSEG forward multiple.
The suggestion by the company that it is returning $2.5bn to shareholders is somewhat disingenuous. A part of the buy back will be to offset dilution from ever growing stock based compensation awards. Awarding stock to insiders is super complicated at LSEG. It issues RSUs and PSUs at nil cost, it has a deferred bonus plan (DBP) also awarded in shares at nil cost, it has a save as you earn scheme (SAYE) - salary sacrifice purchases - where shares are sold to employees at 20% below market price, and finally it has an international share incentive plan (ISIP) where employees buy two shares and get one for free (so equivalent to a 33% discount). External investors need to be mindful of this prior to investing as it comes out of corporate shareholder capital (there’s no such thing as a free lunch).
Would be a disaster for the UK if moved its listing to the US. The symbolism of what it represented would be the worst bit about it
Many thanks as always, but why is LSEG producing such appalling returns on equity whilst margins are sky high?